
Georgia’s incoming insurance chief wants to ban credit scores and ZIP codes from auto rates, a move that could shift who pays more and who pays less.
Story Highlights
- Commissioner-elect Keisha Sean Waites plans to bar credit and ZIP code factors in pricing.
- Two Georgia Senate bills outline bans on credit data and geographic rating.
- Premium gaps by credit score in Georgia are large, so costs would likely be redistributed.
- State law and agency authority could limit how fast or how far a ban can go.
What Georgia’s New Insurance Chief Says She Will Do
Commissioner-elect Keisha Sean Waites said credit scores and ZIP codes “have nothing to do” with auto insurance risk and pledged to remove them from pricing in her first 100 days. The statement came in a November 2026 interview and set a clear early agenda. She framed the plan as a fairness fix for families facing rising bills. Her office will still need to show how companies should rate risk without those data points.
Waites’s push matches concrete bills already drafted at the Capitol. One bill would stop insurers from using credit information and credit scores in underwriting, rating, and adverse actions. It lists a July 1, 2026 effective date. Another bill would bar use of geographic classifications in vehicle insurance, applying to policies issued, renewed, or changed on or after January 1, 2027. These texts give lawmakers clear levers to act.
How the Change Could Reshape Who Pays
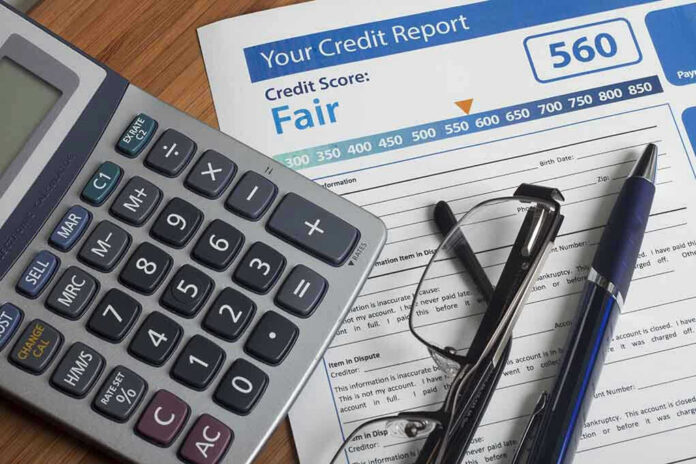
Premiums in Georgia now vary a lot by credit tier. One analysis found about $3,139 a year for a driver with poor credit versus $1,300 for a driver with excellent credit, a gap of $1,839. If the state bans credit scoring, insurers would still expect the same claims. They would shift costs using other allowed factors. That likely means lower premiums for some poor-credit drivers and higher premiums for some excellent-credit drivers.
Geographic rating changes could also move money between areas. Insurers say they set territories because claims, theft, repair costs, and traffic differ by where a car is garaged. Ending ZIP code or territory pricing could raise rates in some lower-risk places and lower them in higher-risk places. That is why local leaders and drivers in safer counties are watching closely. The core question is how to price risk without blunt location inputs.
What Georgia Law Allows Today
Georgia already regulates both credit data and geography in insurance. State code governs how credit information can be used in personal insurance and bars unfair practices. Some current limits already apply to what may be included in credit-based insurance scores. A wider ban would have to fit within those statutes or change them. That means the General Assembly’s choices will shape the final map of any reform.
Legal authority is a live issue. Analysts tracking the Georgia Supreme Court’s recent “EVA” decision say the Insurance Commissioner may not be able to impose sweeping bans alone. Broader changes likely require legislation and formal rulemaking. One reported credit ban effort went to committee without a vote, showing the hill that remains. The path runs through hearings, industry pushback, and negotiations on timing and scope.
Why Both Sides Are Fired Up
Supporters argue credit is a poor stand-in for driving risk and can punish people who never filed a claim. They see families squeezed by forces they cannot control. Opponents warn that removing predictive tools can force cross-subsidies and may cause some insurers to pull back. They fear higher bills for careful drivers in safer areas. Both sides agree rates must track real losses. They split on whether credit and ZIP codes do that fairly.
Under President Trump and a Republican Congress, many Americans still see rising costs and a system that serves insiders first. Georgia’s fight fits that mood. People on the right resent hidden cross-subsidies. People on the left resent models that mirror wealth gaps. The public wants proof, not slogans. The next step is clear: show the data that credit and ZIP codes add real risk signal, or build a new model that prices risk without them.
Sources:
townhall.com, legis.ga.gov, wsbtv.com, peachpundit.com, liveinsurancenews.com, pjmedia.com, codes.findlaw.com